Texas Airbnb & VRBO DSCR Loans

Financing for short-term rentals in Austin, San Antonio, Houston, Dallas, the Hill Country, and the Gulf Coast.

If you own or want to buy a short-term rental in Texas, a DSCR (debt service coverage ratio) loan qualifies you on what the property earns. Not your personal tax returns, not your W-2s, not your debt-to-income ratio. We shop the loan across our lender network to find the one program that fits your deal, instead of running you through a single lender's fixed rulebook.

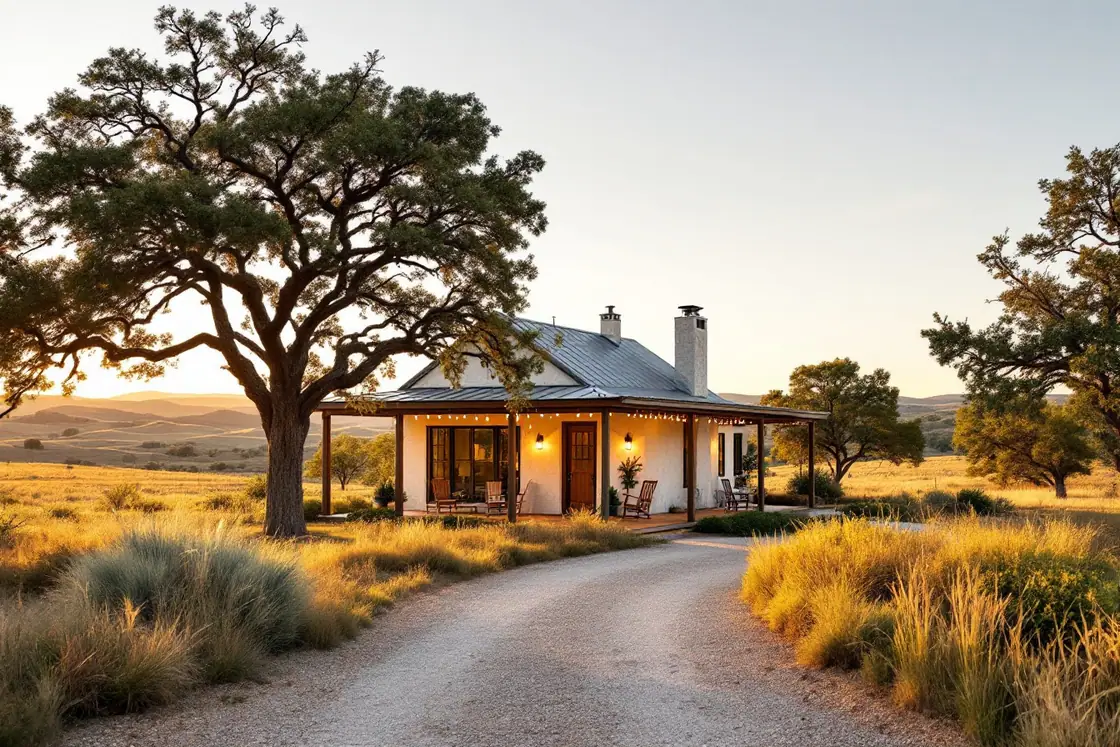
Limestone short-term rental home with a covered porch under live oaks in the Texas Hill Country at golden hour

Texas short-term rental DSCR loan requirements

Minimum credit score for this program
660
Maximum LTV at a 660 FICO
75%
Better credit can open up more favorable terms.
Loan amounts
$150K to $650K
To close, in most cases
7 to 10 days after the appraisal
Sometimes faster, depending on your file and, on a purchase, the agents involved.
DSCR ratio
Down to 0.75 accepted. Negative cash flow is OK, though pricing climbs the lower you go.
Rate options
30-year fixed, 40-year fixed with 10-year interest-only, or ARM.
Prepayment
Averages 3 years, up to 5 years depending on the lender. Shorter terms (1 year or no prepay) are available at a cost in points and fees.
Transaction types
Purchase and cash-out refinance.
Reserves
None required at a 720+ FICO. Tiered below that, and some lenders are more flexible depending on the file.
Property type
1 to 4 unit residential, in town or rural. Rural carries roughly a 5% LTV reduction.
Ownership
LLC allowed, with a personal guaranty from the borrower.

How Texas short-term rental income actually qualifies

Here's where a lot of borrowers get confused: an AirDNA projection alone doesn't carry the deal. The qualifying number comes from one of two places.

  • The appraiser's rental analysis

    Qualifies the deal

    The standard short-term or comparable rental schedule that comes with the appraisal. On a new purchase, this market analysis carries the weight.

  • Documented rental history

    Qualifies the deal

    If the property already has a track record on Airbnb or VRBO, bring that booking history. It strengthens your file.

  • An AirDNA projection on its own

    Sanity check only

    Some lenders will glance at one as a sanity check. It does not carry the deal.

Why work with a broker instead of one direct lender

Most DSCR sites you'll find are a single lender with one set of guidelines. If your deal doesn't fit their box, you're stuck.

We don't underwrite in-house. Instead, we take your scenario to the lenders in our network who compete for it, and place the loan with whoever gives you the strongest combination of pricing, LTV, and terms for that specific property. If one lender's overlay (an extra rule on top of the standard guidelines) kills the deal, we have others to try. That's the entire point of using a broker instead of a single-source lender.

Same credit score, different reserve requirement

Here's an example of what shopping the loan actually does for you. Reserve requirements on our programs are tiered by credit score.

  • 720 and up Can qualify with zero reserves in the bank
  • 680 to 720 Typically 3 to 6 months of PITIA
  • 660 to 680 Up to 12 months of PITIA

PITIA is the full monthly payment: principal, interest, taxes, insurance, and any association dues.

On paper, that looks like a hard rule. In practice, some lenders in our network are more flexible on reserves than others, depending on the rest of your file. A borrower who looks stuck at a 12-month reserve requirement with one lender might qualify with 3 to 6 months at another, even at the same credit score. A single-lender site can't offer you that, because it only has its own rulebook to work with.

Picking the lender isn't just about who has the lowest advertised rate. It's about who underwrites your specific situation the way you need it underwritten.
Texas short-term rental markets we finance

  • Austin

    Still one of the most active short-term rental markets in the state, though the city's permit system means you'll want to confirm zoning before you buy or convert a property. We can talk through what that means for your loan timeline.

  • San Antonio

    A steadier, less saturated market than Austin, with strong year-round demand tied to tourism around the River Walk and the medical center corridor.

  • Hill Country

    Fredericksburg, Wimberley, New Braunfels

    Wine-country and river-town getaways where short-term rentals often outperform long-term lease comps by a wide margin. Exactly the kind of property DSCR financing was built for.

  • Houston

    Medical center and business travel keep demand steady beyond tourist season, which appraisers factor into the rental analysis differently than a pure vacation market.

  • Dallas

    Convention and corporate travel support a different pattern than the Hill Country or the Gulf Coast: shorter average stays and more weekday demand.

  • Gulf Coast

    Galveston, Port Aransas

    Classic beach-town territory with established rental comps, which usually makes the appraisal process more straightforward than in newer markets.

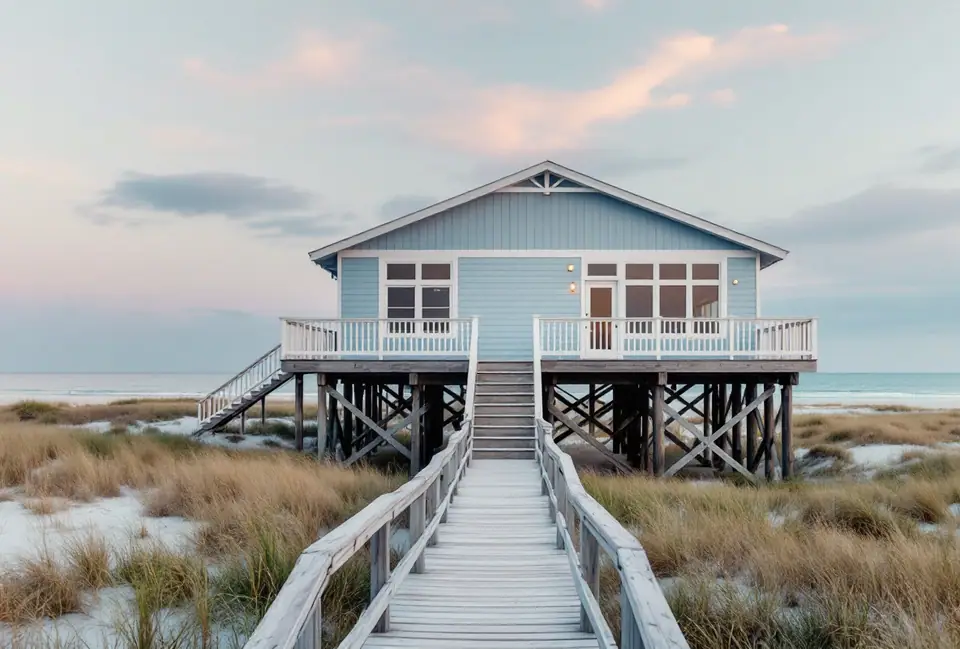
Elevated beach house on pilings behind the dunes on the Texas Gulf Coast

Outside city limits

Hill Country ranch properties, Gulf Coast beach houses off the main strip: rural short-term rentals are eligible too. Expect roughly a 5% hit to your maximum LTV compared to a comparable in-town property, since rural comps and exit liquidity carry more weight in the lender's eyes.

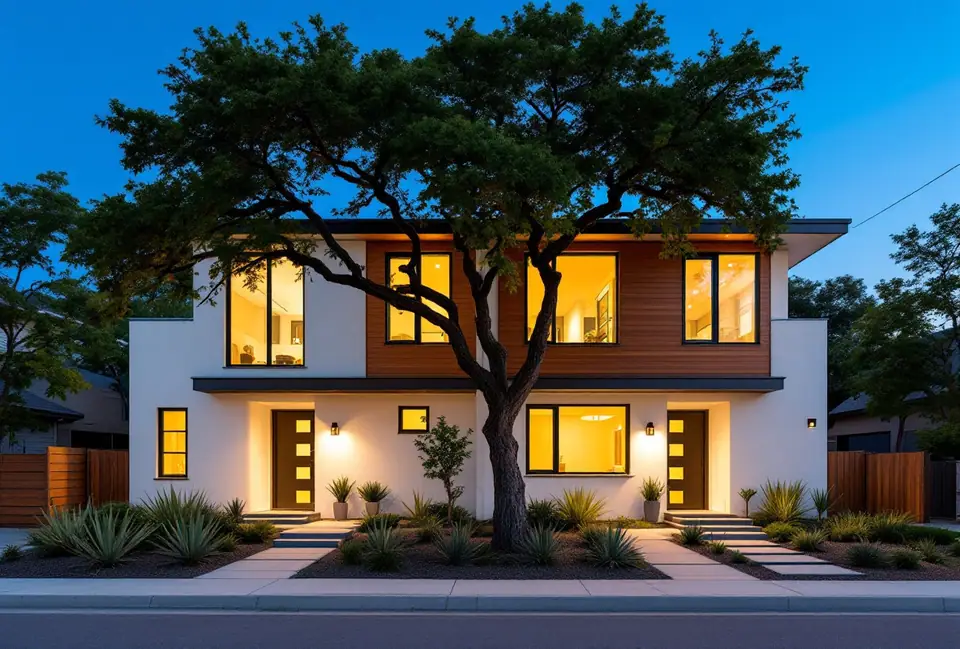
Modern duplex with two front doors on a residential street in Austin, Texas at dusk

Who this loan is built for

This program is designed for experienced real estate investors, not a first Airbnb purchase. If this would be your first investment property, a standard DSCR loan for a long-term rental is generally a better starting point, and we can point you toward that instead.

Eligible properties are 1 to 4 unit residential:

  • Single family homes
  • Duplexes
  • Triplexes
  • Fourplexes

A quick example of how this plays out

Say you're looking at a three-bedroom Hill Country property near Fredericksburg.

Purchase price
$400,000
Market rent the appraiser's short-term rental schedule supports
$3,200 a month

Your credit is 690

Depending on which lender in our network fits your file best, you might land anywhere from:

  • A 3-month to a 6-month reserve requirement
  • A purchase LTV in the high 70s
  • A rate priced around a DSCR near 1.0 to 1.1 for that rent-to-payment ratio

Change the credit score to 725

The reserve requirement can drop to zero with a different lender entirely.

Same property, same rent, different outcome because of which program you're placed in.

An illustration, not a quote or a commitment to lend.

Check Your DSCR Eligibility

Why we charge points upfront

Some lenders roll their compensation into a higher rate so you pay nothing at closing. We do the opposite and charge points upfront, because the lower rate that results directly improves your DSCR and your monthly cash flow, which is the entire qualifying metric on this loan.

For you as the property owner, the monthly cash flow usually matters more than what you paid to get there.

Common questions about Texas Airbnb DSCR loans

Do I need existing Airbnb booking history to qualify?

No. A new short-term rental can qualify using the appraiser's rental analysis. Existing booking history helps but isn't required.

Can I close this loan in an LLC?

Yes. Most serious investors hold short-term rental properties in an LLC for liability separation, and that's standard for this loan type. The LLC doesn't remove you from the loan personally, though. You'll still sign the loan documents individually and personally guarantee the debt.

What if my city restricts short-term rentals?

Check local zoning and short-term rental permitting before you buy or convert a property. Austin in particular has an active permit process. We can help you think through how that affects your loan and your appraisal.

Is there a maximum number of properties I can finance this way?

There's no personal cap on our end. It depends on the specific lender's guidelines for your file, which is part of why we shop multiple lenders rather than being boxed into one.

Do you work with foreign national borrowers?

Not on our short-term rental programs specifically. Our standard long-term rental DSCR loans have separate options, so it is worth a conversation if that applies to you.

Does checking my eligibility pull my credit?

No. The credit range you pick on the form is your own estimate, and nothing on this site pulls, checks, or touches your credit. A credit report only comes into play later, if you decide to move forward with an application.

Get your scenario in front of the right lender

Every deal is different. Tell us the numbers and we'll tell you which lender in our network fits it best.

Step 1 of 911%
Step 1 of 9. What are you looking to do?

What are you looking to do?

Takes about 60 seconds.

Provided by Internet Loans Direct. Equal Housing Opportunity